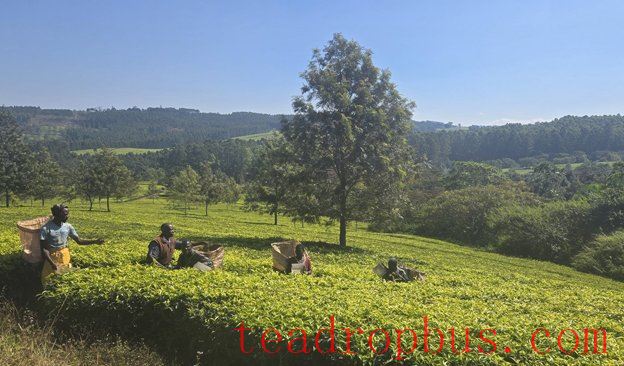
To improve gender equality and enhance tea workers' livelihoods, Malawi is advancing digital payments across its tea supply chain. Photo credit: The Tea Association of Malawi.
The Tea Association of Malawi Limited (TAML) is working to digitize wage payments for workers across the entire tea industry. This initiative aims to promote inclusive growth, enhance productivity, and improve the livelihoods of smallholder tea farmers and laborers, with a particular focus on empowering women within the sector.
TAML partners with Better Than Cash Alliance, working in tea estates in Thyolo and Mulanje to support their transition from cash to digital payments. This alliance is a UN-based partnership of governments, companies and international organizations that accelerates the transition from cash to digital payments.
The Malawi tea sector has an annual monetary flow of $54.8 million among its workforce (approximately 60,000 plantation workers and 22,000 smallholder farmers). To date, the Malawi tea sector has digitized wage payments for 20,000 tea workers and has distributed over $7.2 million digitally since April 2025.
Benefits of Digital Payment
In Malawi, many tea workers and smallholder farmers face long waits to receive their pay. Carrying cash creates safety risks, and limited access to credit pushes people towards expensive informal loans. Digitalization also helps employers reduce the time, cost, and security risks associated with handling large amounts of cash.
Satemwa Tea and Coffee Estate in the Shire Highlands installed an ATM on site eight years ago to support digitalization and will start trial payments through the TAML project at the end of this month. “The cashless ecosystem needed to improve significantly before the current initiative could be both convenient and cost-effective,” Satemwa director Alexander Kay wrote in an email to STiR Coffee and Tea. “Much work still needs to be done.”
Local tea factories face substantial costs associated with cash payments. Specifically, a factory employing 11,200 workers incurs annual expenses of about $37,000 just for managing cash transactions. Across the sector, these expenses exceed $200,000. Conversely, both farmers and workers appreciate the benefits of digital payments, such as greater convenience and enhanced savings options.
The initiative has also facilitated access to more than $500,000 in formal loans for the workers. For instance, digital payment access enabled Rhoda Lucius, a young tea worker in Thyolo, to secure her first formal loan, purchase a tea field, and invest in her family's future.
“There are many positive stories whereby workers and smallholders have been able to access loans through the banking system to buy land, support new businesses, educational needs, etc. at reasonable rates relative to the loan shark systems that have prevailed here,” Kay explained. “The Better Than Cash initiative will only build on this in time.”
Industry-Wide Adoption
Fees associated with current digital transactions are a key barrier, with costs for cashing out and sending money across networks ranging from 1.76-4.11% and 6-23% of the transaction value, respectively. This fee structure makes digital payments less attractive compared to traditional cash transactions. So, financial service providers (FSPs) need to revisit their propositions to the tea sector.
Currently, TAML is hiring a consultant to develop a comprehensive digital payment ecosystem tailored to the tea sector's needs. Essential improvements include broader access to necessary technologies such as mobile phones and lower fees for digital services. Offering relevant financial products such as savings accounts, credit options, insurance, and pensions is also critical.
The consultant is to prepare a detailed implementation plan for new tea-growing states, develop and oversee training programs, and create tools (policy, process monitoring, and evaluation dashboards) for the tea sector’s engagement with FSPs based on the UN principles for responsible digital payment and the Reaching Financial Equality for Women, a strategic framework and action plan.
Moreover, the consultant will facilitate the development of a micro-merchant ecosystem to promote digital usage, develop and implement a scaling roadmap targeting sector-wide adoption, and support the design of additional value-added financial products and solutions in collaboration with selected FSPs.